3. Non-preferential origin of product at the terminal
Introduction
The non-preferential origin of a product is required:
- For customs declarations, for example on release for free circulation from the customs warehouse or on export;
- For the application of commercial policy measures such as anti-dumping duties and sanctions; and
- Where a customer requests non-preferential origin documentation.
The approach depends on whether the product has undergone an operation at the terminal that may affect its origin:
- where the product leaves the terminal unchanged, its origin follows the origin recorded for the relevant inbound parcel(s);
- where the product has been blended or otherwise processed, its origin is established in accordance with the steps set out below.
Origin determination for goods that remained unchanged during their stay at the terminal
Where a product leaves the terminal without having undergone any processing or blending that has affected its non-preferential origin, VTTI relies on the country of non-preferential origin registered for the relevant parcel upon first registration.
Before the origin information of an unchanged product is used for a customs declaration, origin document or other customs or compliance purpose, CS verifies that:
- the outbound product can be traced to the relevant inbound parcel(s); and
- no operation has taken place that may have affected its origin.
The following operations do not affect origin:
- operations limited to the storage and preservation of the product, such as circulation or heating in the tank;
- "minimal operations" listed in article 34 UCC-DA, the following of which may be relevant for VTTI's business:
- operations to ensure the preservation of products in good condition during transport and storage or operations facilitating shipment or transport of the product;
- simple operations consisting of the removal of dust, sifting, screening or washing;
- Changes of packing and the breaking-up of consignments, the simple placing in bottles, cans, flasks and all other simple packaging operations;
- Marking;
- Change of use;
- A combination of two or more of the above operations.
- "simple processes" specified in the Commission's list rules. For example, for products of Chapter 27, the following operations are regarded as simple processes not conferring origin:
- cleaning;
- decantation;
- desalination;
- water separation;
- filtering;
- colouring;
- marking;
- or any combination of the above.
If the product didn't undergo any processing, or if its clear that the operation falls under one the minimal operations described above, CS determines the non-preferential origin of the product on the basis of the major portion rule: The
origin of the final product is the country or territory where the major
portion of the materials originated. Where the final product is classified under Chapter 1 to 29, or 31 to 40 (the majority of products handled by VTTI), the major portion rule is applied based on the weight of the input materials. Where the final product is classified in another HS-Chapter, the major portion rule is applied based on the value of the input materials. In such case, CS must reach out to the customer to provide information regarding the value of each component.
The origin of the components that determine the outcome must be substantiated by supporting documentation.
In case of doubt, CS reaches out to the customs specialist at the terminal to assist with application of the major portion rule.
If the product has undergone processing at the terminal that exceeds the minimal operations described above, next step is to assess of that processing was sufficiently substantial to confer EU origin to the product. The framework for this assessment is described in the next section.
Non-preferential origin determination following blending or processing
Blending or processing at the terminal may
From a system perspective, this is triggered as follows: When an activity at the terminal results in registration of a new parcel, the country of origin of that parcel is registered in VTTI's ERP system as "QU", meaning "countries and territories not specified". The use of "QU" reflects that no specific country of non-preferential origin has yet been established. It does not constitute an origin determination and must not be used as the country of origin in a customs declaration, origin document or other external communication.
Before the non-preferential origin is required for placing the product under a subsequent customs procedure, or for another customs or compliance purpose, the origin of the resulting product is established by CS, assisted by the customs specialist at the terminal. This assessment is conducted on the basis of the information provided by the customer in combination with the information available in VTTI's systems.
Check 1: Annex 22-01 UCC-DA
BasedCheckon2:article 32 UCC-DA, theList rulesof Annex 22-01 apply if the end-product is listed in that Annex. This means that if the product was processed at the terminal, that processing is deemed to confer EU origin to the product if the rule in Annex 22-01 is met.- When the product concerned is not listed in Annex 22-01 UCC-DA, VTTI takes
into accountthe European Commission's table of non-preferential originrules.rules ("list rules") into consideration. Althoughthesethe list rules are not legally binding, they reflect the European Commission's interpretation of Article 60(2) UCC and are commonly applied in practice by customs authorities and chambers of commerce.For example, the following rule applies to products classified under HS heading 2707:
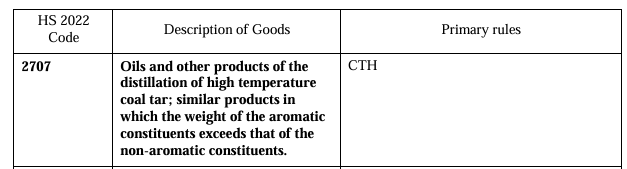
- This means that processing carried out at the terminal is deemed to confer EU non-preferential origin on a product classified under HS heading 2707, provided that the non-EU originating materials undergo a change in tariff heading (CTH). In other words, the rule is satisfied where the non-EU originating input materials are classified under an HS heading other than 2707 and the resulting product is classified under HS heading 2707.
According to the case law of the Court of Justice, substantial processing may also exist without a change of tariff heading, where the processing results in a product with properties and a composition of its own that it did not have before the process (Case C-260/08, HEKO). This is explained in more detail later in this procedure.
The list rules further specify that fForor products of Chapter 27, an operation at the terminal confers origin where it consists of:
- a chemical reaction;
- atmospheric or vacuum distillation, or extraction by means of selective solvents (
headings 27.07, 27.10applicable to27.13headings 2707, 2710 to 2713 and27.15)2715); - processing resulting in a change of tariff heading, where the heading rule so provides; or
- deliberate and proportionally controlled mixing or blending of materials to conform to predetermined specifications, resulting in a product with physical or chemical characteristics that are relevant to its purposes or uses and different from those of the input materials.
If atcheck 2 doesn't lead to a clear conclusion, check 3 should be applied.
Check 3: Qualitative test
According to the terminalcase is performed on the instructionlaw of the customer,Court of Justice, even if the criteria described under check 1 and 2 are not met, a product may still be considered substantially processed where the assessmentprocessing results in a product with properties and a composition of its originown consequencesthat takesit placedid innot closehave consultation betweenbefore the terminalprocess and(Case theC-260/08, customer.HEKO). The customer determines the composition and purpose of the blend. When instructing a blend, the customer therefore indicates:
the components and the proportions to be used;whether the blend is performed to meet a predetermined specification and, if so, which specification (for example a grade or a limit value for RON, sulphur content or viscosity); andwhether, in the customer's view, the blend confers origin, together with the supporting information on which that view is based.
the blend order;the quantities, product descriptions and CN codes of the components and the resulting product; andwhere available, quality or analysis data of the components and the resulting product.
In performing this check, the customs specialist takes the following indicators into account:
- Blending towards a specification. Components are blended in controlled proportions to obtain a product that meets a specification the components did not meet individually. This indicates origin-conferring blending.
- Addition to a base product. Product is added to a base product that already meets the relevant specification, for example to optimise margin, and the resulting product still meets the same specification. No new product is created, so the operation does not confer origin.
- Change of product description or CN code. A resulting product with a different product description or CN code than the major part of the components (by quantity) is a strong indication of origin-conferring blending.
- Same CN code. The fact that the components and the resulting product fall under the same CN code does not exclude origin-conferring blending, provided the resulting product has technical characteristics it did not have before blending.
If the conclusion following checks 1-3 is that the operation at the terminal doesn't confer origin to the product, the origin must be determined on the basis of the Residual rule.
Residual rule
Based on the residual rule, the origin of the final product is the country or territory where the major portion of the materials originated. Where the final product is classified under Chapter 1 to 29, or 31 to 40 (the majority of products handled by VTTI), the major portion rule is applied based on the weight of the input materials. Where the final product is classified in another HS-Chapter, the major portion rule is applied based on the value of the input materials. In such case, CS must reach out to the customer to provide information regarding the value of each component.
The origin of the components that determine the outcome must be substantiated by supporting documentation.
In case of doubt, CS reaches out to the customs specialist at the terminal to assist with application of the major portion rule.
Information to be taken into account during the origin assessment
Blending at the terminal is performed on the instruction of the customer, and the assessment of its origin consequences takes place in close consultation between the terminal and the customer. The customer determines the composition and purpose of the blend. When instructing a blend, the customer therefore indicates:
- the components and the proportions to be used;
- whether the blend is performed to meet a predetermined specification and, if so, which specification (for example a grade or a limit value for sulphur content); and
- whether, in the customer's view, the blend confers origin, together with the supporting information on which that view is based.
The terminal's customs specialist performs a reasonableness check on the customer's information. The check compares it with the information available in VTTI's systems, such as:
- the nomination;
- the quantities, product descriptions and CN codes of the components and the resulting product; and
- where available, quality or analysis data of the components and the resulting product.
In line with the contractual arrangements between VTTI and the customer, the customer is responsible for the accuracy and completeness of the information provided in relation to the blend, including its specification and origin consequences. VTTI relies on this information, subject to the reasonableness check described above. Where the customer's information is incomplete or inconsistent with the information in VTTI's systems, the customs specialist requests clarification from the customer before the blend is treated as origin conferring. Where the matter remains unresolved, the blend is not treated as origin conferring.
The calculation uses the quantities and recorded origins of the input parcels in VTTI's ERP system.In line with VTTI's practice, materials originating in different EU Member States are aggregated as EU origin.The origin of the components that determine the outcome must be substantiated by supporting documentation.
Annex 22-01Completion. The customs specialist first checks whether Annex 22-01 UCC-DA contains a rule for the relevant heading or subheading. If so, the operation is tested against the primary rule in that Annex. Where the primary rule is not met, the chapter residual rule in that Annex applies. Both are legally binding (Article 32 UCC-DA).Article 60(2) UCC and the list rules. Where the product is not covered by Annex 22-01, origin is determined under Article 60(2) UCC. The Commission's list rules for the relevant chapter are applied as guidance for interpreting that provision. The list rules are not legally binding and may not lead to an outcome that contradicts Article 60(2) UCC.Minimal operations. Operations listed in Article 34 UCC-DA, and the simple processes listed in the relevant chapter note of the list rules, never confer origin.Residual rule. Where the operation does not confer origin, whether because it is a minimal operation or because the primary rule is otherwise not met, the chapter residual rule of Annex 22-01 or of the list rules applies. This is in most cases the country in which the major portion of the materials originated, determined on the basis of weight or value depending on the chapter.Value-based rule. Where the applicable rule is based on value, the customer provides the value information required.
Once the determination has been completed, CS replaces "QU" with the determined country of non-preferential origin in the ERP system. The following are retained as part of the origin audit trail:
- the outcome and basis of the determination, together with the relevant supporting information;
- the customer's
blend instruction;nomination; - the information provided by the customer on the specification and origin consequences of the blend; and
- the outcome of the reasonableness check.
A work instruction for non-preferential origin determination at the terminal, including practical examples, is included here.here [TBD]
Non-preferential origin documentation
At the request of a customer, VTTI can provide or facilitate non-preferential origin documentation for an outbound shipment. Two types are used:
- a Certificate of origin issued by the competent authority (in the Netherlands, the Chamber of Commerce (KVK)) at the request of the exporter. VTTI provides the information and supporting documentation required for the application;
- Terminal Origin Declaration issued by VTTI.
Before providing or facilitating either document, CS verifies that the non-preferential origin has been properly established.
A Terminal Origin Declaration is issued in one of two forms:
- Single origin: it states the non-preferential origin of the outbound product as established under this section.
- Breakdown: where the outbound quantity consists of commingled parcels of different origin that cannot be attributed to a single origin, it lists the relevant parcels and quantities with their recorded country of origin. For each parcel, it indicates whether the origin is substantiated by origin documentation. Where it is not, the origin is stated as "as declared by the customer, not substantiated". A breakdown is not issued in place of an origin determined following blending.
A Terminal Origin Declaration:
- identifies the terminal, the outbound product, quantity and shipment;
- states that it concerns non-preferential origin determined in accordance with Articles 59 and 60 UCC, on the basis of information provided by the customer and VTTI's own records;
- states that it is not a proof of preferential origin and cannot be used to claim preferential tariff treatment;
- is signed by a person authorised to do so; and
- is never titled "statement on origin" or "certificate of origin", to avoid confusion with preferential proofs of origin and official certificates.
Where the origin is an EU Member State, the declaration may state "European Union", with the Member State where the product was blended where relevant (for example "European Union (blended in the Netherlands)").
A document proving origin may also be issued in accordance with the rules of origin of the country of destination (Article 61(3) UCC). Where a customer requests an origin statement under such rules, CS refers the request to the terminal's customs specialist.
Any document prepared or facilitated by VTTI must be consistent with the origin information recorded in the ERP system. VTTI will not provide, facilitate or support an origin document where the non-preferential origin has not been established or material concerns remain unresolved.
Follow-up and escalation
Any doubt concerning any of the following must be resolved before the origin is used for customs or compliance purposes:
- the origin of the input materials;
- the customs classification of the relevant products;
- the nature and purpose of the operations performed;
- the attribution of commingled product; or
- the applicable non-preferential origin rule.
The terminal's customs specialist requests any clarification or additional information required from CS, the relevant operational personnel or the customer. The customs specialist may request support from CGT where the matter involves:
- complex or unclear origin rules;
- a material financial or compliance impact;
- possible exposure to trade measures; or
- engagement with a competent authority.
VTTI will not use or communicate a country of non-preferential origin while material concerns regarding the determination remain unresolved.
Recording and retention
A copy of any origin document issued or facilitated, the underlying determination and the relevant supporting documentation are stored in the Document Management System and linked to the outbound parcel or shipment. CS records the relevant document data in the Cargo Documents module in ERP. Records are retained for at least seven years.