Customs valuation methodology selection and application
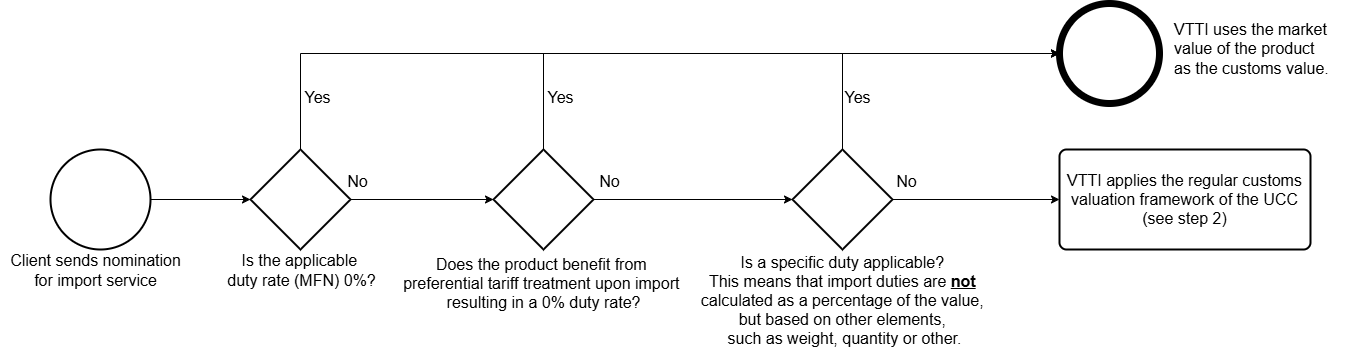
Step 1: Assess if pragmatic approach may be applied
Step 2: Assessment of the applicability of the transaction value method
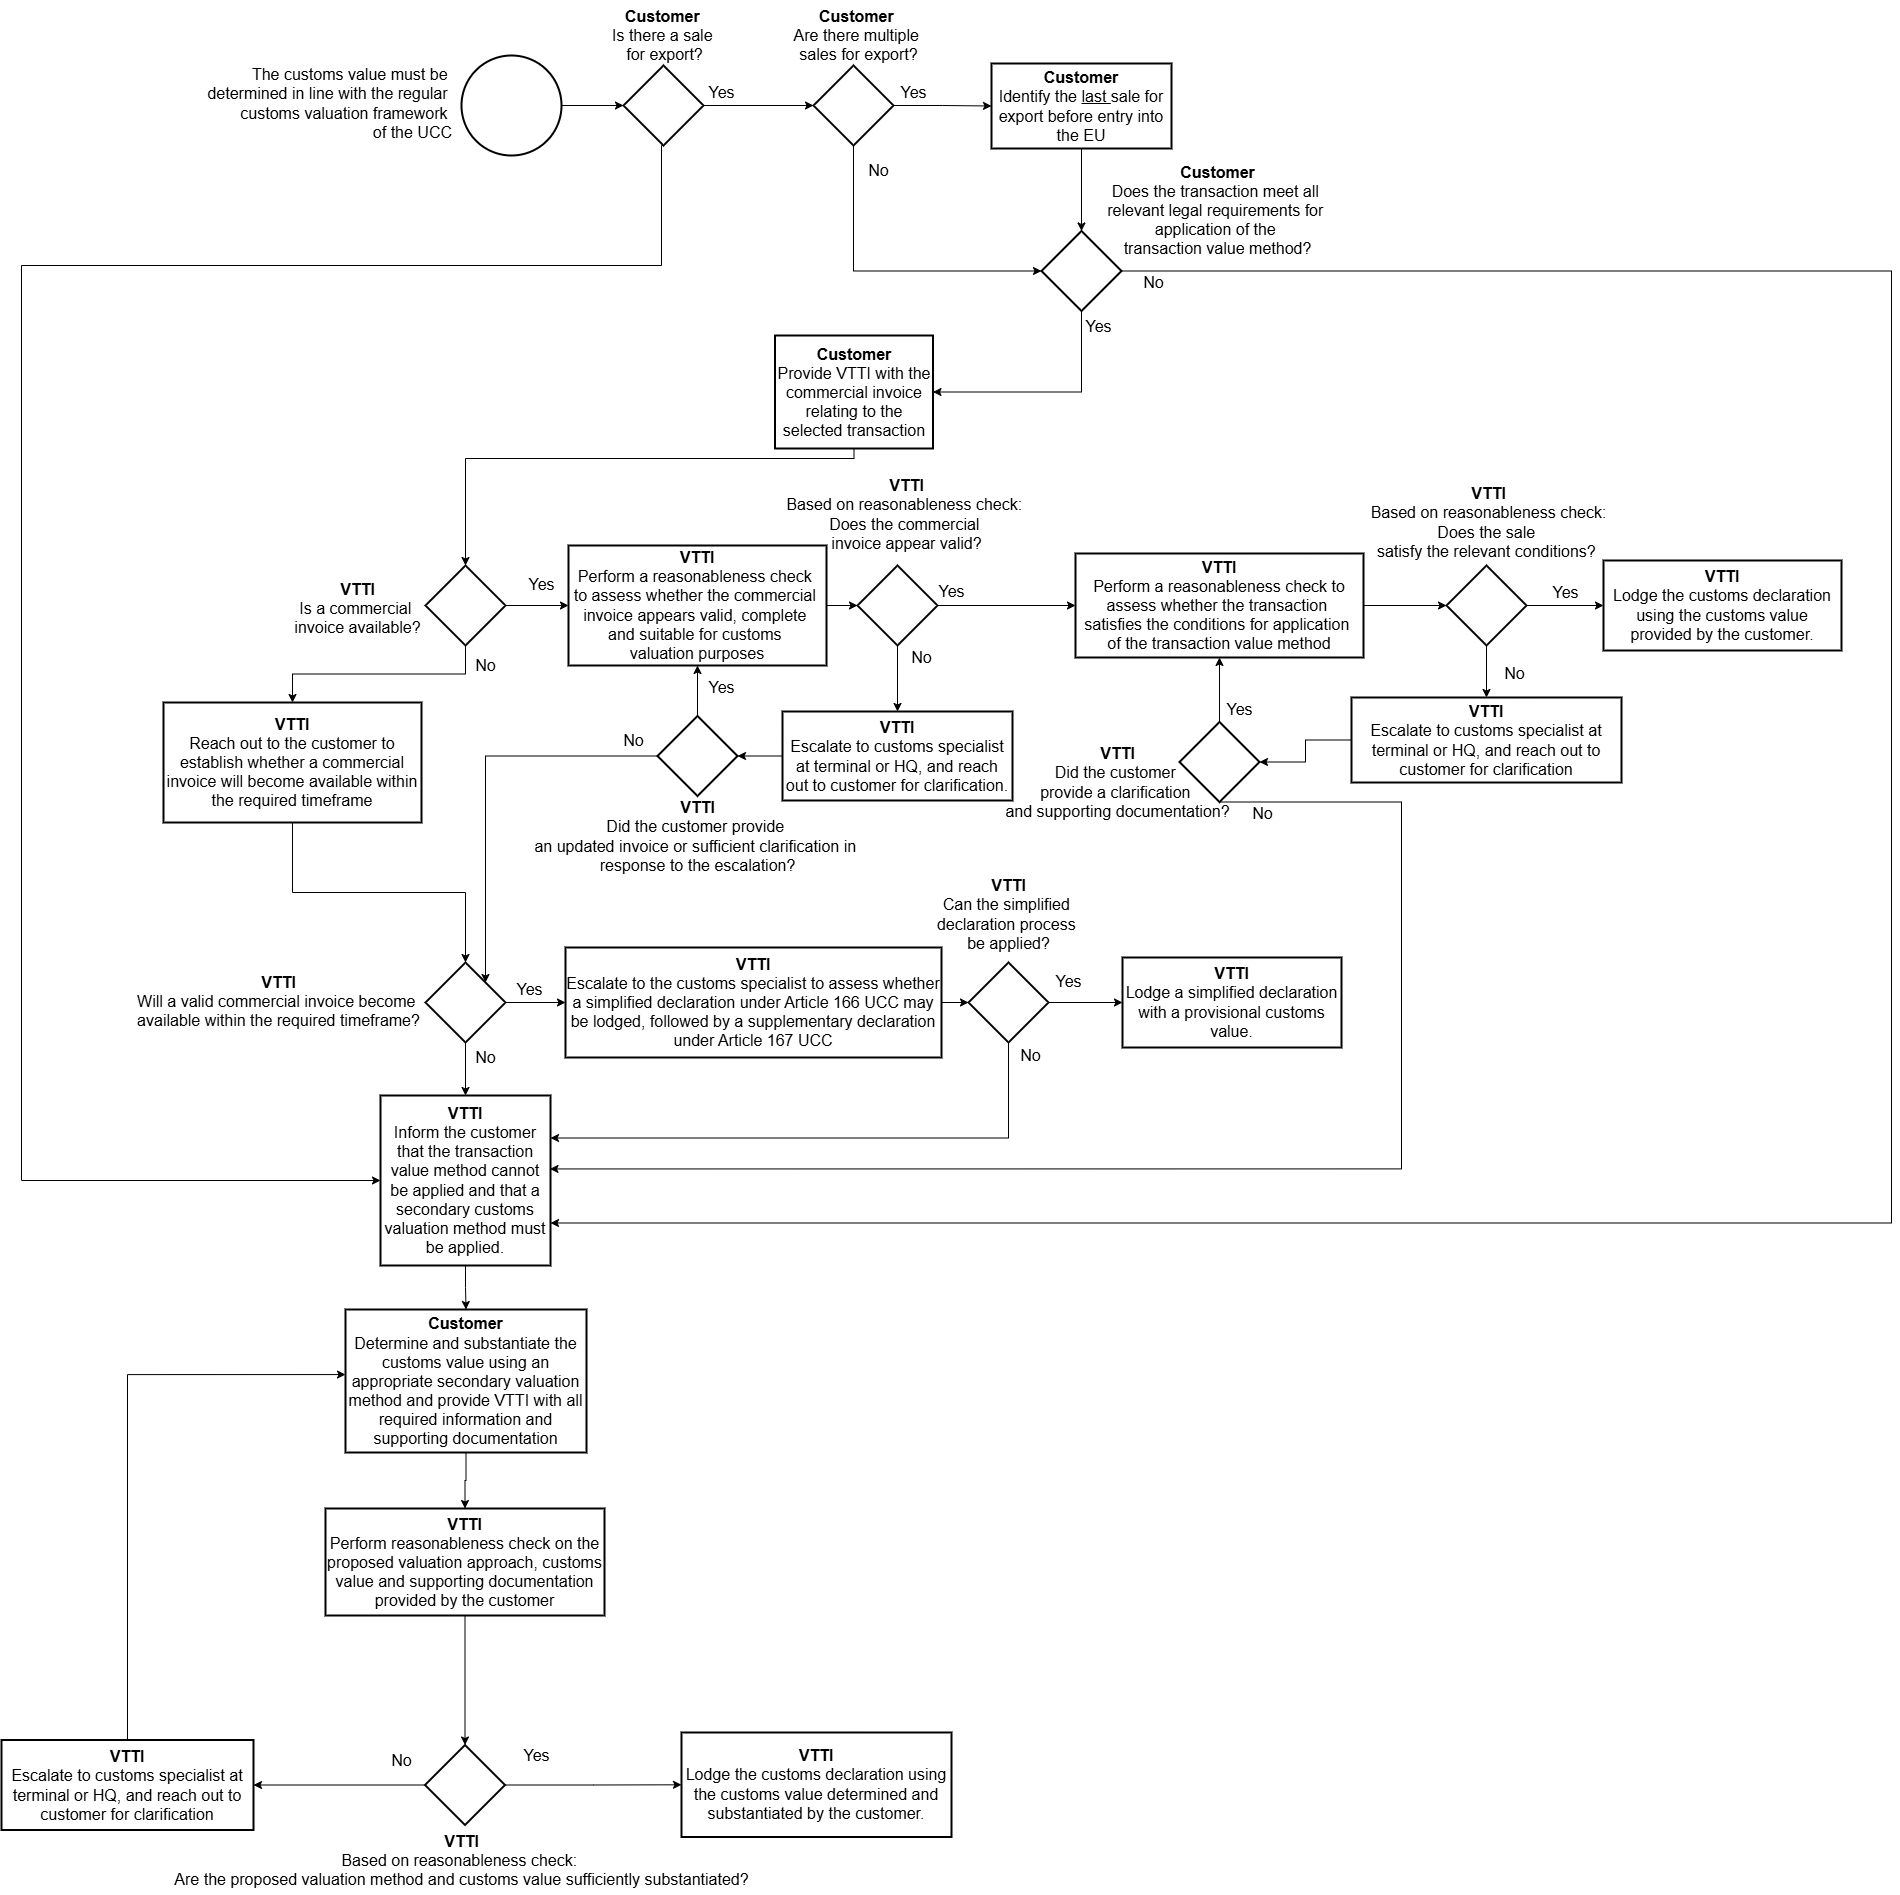
The commercial invoice relating to the transaction identified in Step 2.1 is required as a supporting document for the declared transaction value. It is the customer’s responsibility to provide CS with a valid commercial invoice.
CS will perform a reasonableness check to assess whether the invoice appears valid and suitable for customs valuation purposes. This review concerns the apparent validity and completeness of the invoice.
If deficiencies are identified in the invoice, CS will contact the customer to obtain clarification and/or additional supporting documentation.
In exceptional cases where a final commercial invoice is not yet available, alternative supporting documents, such as a pro forma invoice, a “for customs purposes only” invoice or another preliminary commercial document, may be used, provided that they accurately reflect the transaction value and that this value can be substantiated by the underlying commercial documentation. Before relying on such alternative documentation, CS will consult the customs specialist at the terminal or VTTI HQ.
Where the customer is unable to provide the required commercial invoice at the time of importation but confirms that the invoice will become available at a later stage, CS may, subject to the applicable conditions, submit a simplified customs declaration in accordance with Article 166 UCC. The simplified declaration will contain a provisional customs value based on the information available at the time of importation. Once the commercial invoice becomes available, CS will determine the final customs value in accordance with the transaction value method and submit that value by means of a supplementary declaration pursuant to Article 167 UCC. Before using this simplified declaration procedure, CS will consult the customs specialist at the terminal or VTTI HQ.
If a valid commercial invoice is available and the reasonableness check does not identify any unresolved deficiencies, it must also be verified whether the other conditions for application of the transaction value method are met. See Step 2.3.
If no valid commercial invoice is available and the customer is unable to provide one at a later stage, the transaction value method cannot be applied. CS will inform the customer and escalate the matter to the customs specialist at the terminal or VTTI HQ. The customer must determine and substantiate the customs value in accordance with an appropriate alternative valuation method as described in Step 3 and provide CS with all information and supporting documentation required to prepare the customs declaration. VTTI may discuss the proposed valuation approach with the customer and perform a reasonableness check, but responsibility remains with the customer. CS will not lodge the customs declaration until a sufficiently substantiated customs value has been provided and any material concerns have been resolved.
In addition to verifying the availability and apparent validity of the commercial invoice under Step 2.2, it must be assessed whether the transaction identified in Step 2.1 satisfies the conditions for application of the transaction value method.
This assessment is intended to verify whether the conditions set out in Article 70(3) UCC are met.
In short, the transaction value method cannot be applied where:
- the buyer is subject to restrictions regarding the disposal or use of the goods, other than restrictions permitted under Article 70(3)(a) UCC;
- the sale or price is subject to conditions or considerations for which a value cannot be determined with respect to the goods being valued;
- any part of the proceeds of a subsequent resale, disposal or use of the goods accrues directly or indirectly to the seller, unless an appropriate adjustment can be made in accordance with Article 71 UCC; or
- the buyer and seller are related and the relationship has influenced the price.
Given VTTI’s role, VTTI inherently has limited visibility of the supply chain, the underlying chain of transactions and the contractual circumstances surrounding the sale. The customer is therefore responsible for assessing whether the transaction satisfies the conditions for application of the transaction value method. CS performs a reasonableness check based solely on the information and documentation provided by the customer. The reasonableness checks performed by CS are incorporated into the customs valuation checklist available in BzCtrl. The checklist covers both the apparent validity of the commercial invoice and supporting documentation under Step 2.2 and the conditions for application of the transaction value method under this Step 2.3.
The reasonableness checks conducted by CS are incorporated in a checklist in BzCtrl and included here.
If the reasonableness check raises doubts as to whether the transaction satisfies the conditions set out in Article 70(3) UCC, CS will contact the customer and request further clarification and supporting documentation before lodging the customs declaration.
If no unresolved concerns are identified, CS may use the transaction as the basis for applying the transaction value method.
If it is concluded that the conditions set out in Article 70(3) UCC are not satisfied, the transaction value method cannot be applied. CS will inform the customer and escalate the matter to the customs specialist at the terminal or VTTI HQ. The customer must determine and substantiate the customs value in accordance with an appropriate alternative valuation method as described in Step 3 and provide CS with all information and supporting documentation required to prepare the customs declaration. VTTI may discuss the proposed valuation approach with the customer and perform a reasonableness check but responsibility remains with the customer. CS will not lodge the customs declaration until a sufficiently substantiated customs value has been provided and any material concerns have been resolved.
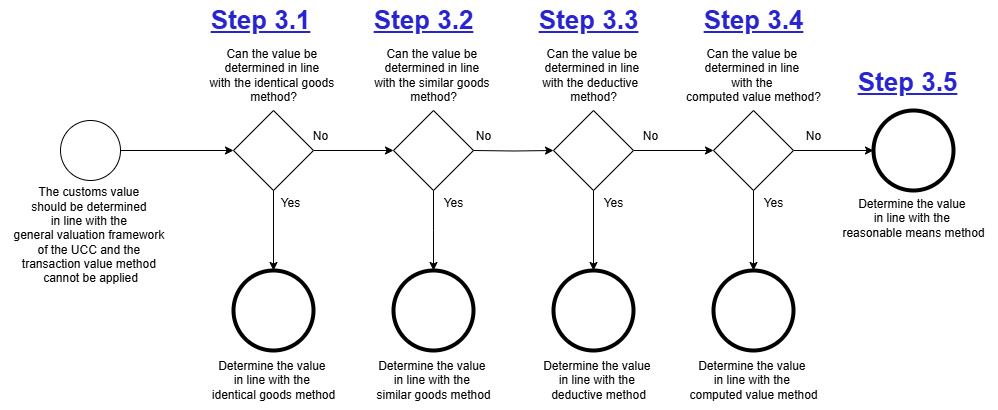
Step 3: Assessment of the applicability of one of the secondary valuation methods
The need to apply a secondary customs valuation method is expected to arise only in exceptional circumstances. In the energy-products supply chains in which VTTI is involved, a commercial invoice and a qualifying transaction will generally be available, allowing the customs value to be determined using the transaction value method.
Where the transaction value method cannot be applied, the customer must assess the secondary valuation methods in the order prescribed by Article 74 UCC and determine the customs value using the first applicable method. The customer must provide CS with the selected valuation method, the resulting customs value and any other information and documentation required for CS to prepare and lodge the customs declaration.
This Step 3 provides only a high-level overview of the secondary valuation methods that may be considered. It is not intended to provide an exhaustive description of the applicable legal requirements or detailed instructions for applying these methods, as the actual assessment lies with the customer.
CS, together with the customs specialist at the terminal or VTTI HQ, will perform a reasonableness check based on the valuation method, customs value and any other information and documentation provided by the customer, and will reach out to the customer for clarification in case of unclarities. VTTI will not lodge the customs declaration if the information provided by the customer gives rise to material concerns that have not been adequately addressed.
The secondary valuation methods must be considered in the order set out below.
- The cost or value of materials, fabrication and other processing employed in producing the imported goods,
- An amount for profit and general expenses equal to that usually reflected in sales of goods of the same class or kind as the goods being valued which are made by producers in the country of export for export to the Union and
- The cost of transport and insurance and loading and handling charges associated with the transport of the imported product, up to the place where the product is brought into the customs territory of the EU.