Import ban fuel 2710 coming from Russian Crude
- Import ban petroleum 2710 obtained from Russian crude 2709
- Scope definition import
- Y693 - Net Exporter Countries of Crude Oil (2024)
- Y694 - Partner Countries listed in Annex LI
- Process flow - Import ban fuel 2710 coming from Russian Crude 2709
- Example - Product CN 2710 petroleum product produced by a refinery in Bulgaria
Import ban petroleum 2710 obtained from Russian crude 2709
Article 3ma
1. It shall be prohibited, as of 21 January2026, to purchase, import or transfer, directly or indirectly into the Union, petroleum products falling under CN code 2710 obtained in a third country fromcrude oil falling under CN code 2709 00 originating in Russia.
For the purposes of the application of this paragraph, at the moment of importation, importers shall provide evidence of the country of origin of the crude oil used for the refining of the product in a third country unless the product is imported from a partner country listed in Annex LI.
Petroleum products imported from third countries which were net exporters of crude oil in the previous calendar year shall be considered to have been obtained from domestic crude oil and not from crude oil originating in Russia, unless a competent authority has reasonable grounds to believe that they have been obtained from Russian crude oil.
2. It shall be prohibited to provide, directly or indirectly, technical assistance, brokering services, financing or financial assistance, as well as insurance and re-insurance, related to the prohibition in paragraph 1.
Scope definition import
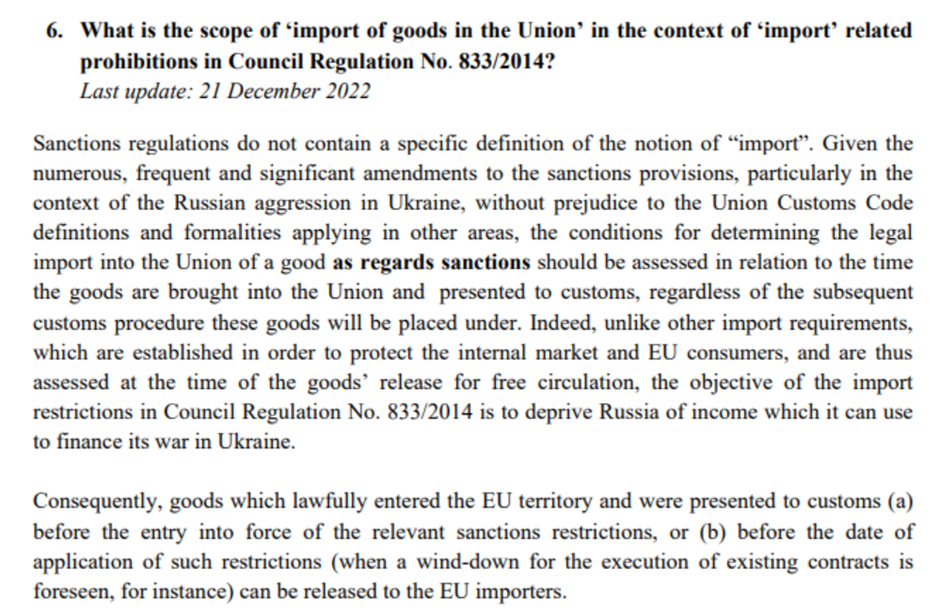
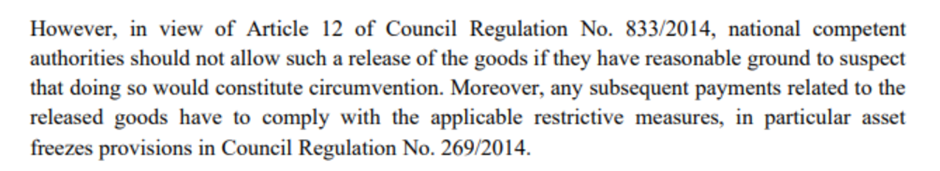
6851f7e0-acf7-4275-8626-d18d3fc15bb9_en
The Regulation itself does not define “import”. In the above passage from the Commission guidance (FAQ, 21 Dec 2022) it can be concluded that “Import” for sanctions purposes is assessed at the moment goods are physically brought into the Union and presented to customs authorities, regardless of the subsequent customs procedure (free circulation, inward processing, warehousing, etc.).
The purpose of the sanctions import ban is to prevent economic access to the EU market by prohibited goods, not to prohibit every customs act. In that regard, economic availability and potential access to the EU market are deemed decisive factors.
Concretely this would mean that placing goods under customs procedures such as Customs warehouse, Inward Processing and, most clearly, the Release for free circulation are considered “Import” as defined in Article 3ma. This is supported by the fact that mid 2025 by accident the Measure was enforced in the customs systems and both declarations for the Release for free Circulation and Inward Processing failed because of a missing statement.
Transit is deemed not to fall within the scope of the Import definition as it does not lead to economic use in the EU. Even though goods are presented when placing goods under transit, that moment merely calls for an assessment as stated in the Guidance. This is also supported by the fact that when transit is banned as well, it is explicitly mentioned in the Regulation. Furthermore, the Import control Measure effectuating the control does not include the NCTS system.
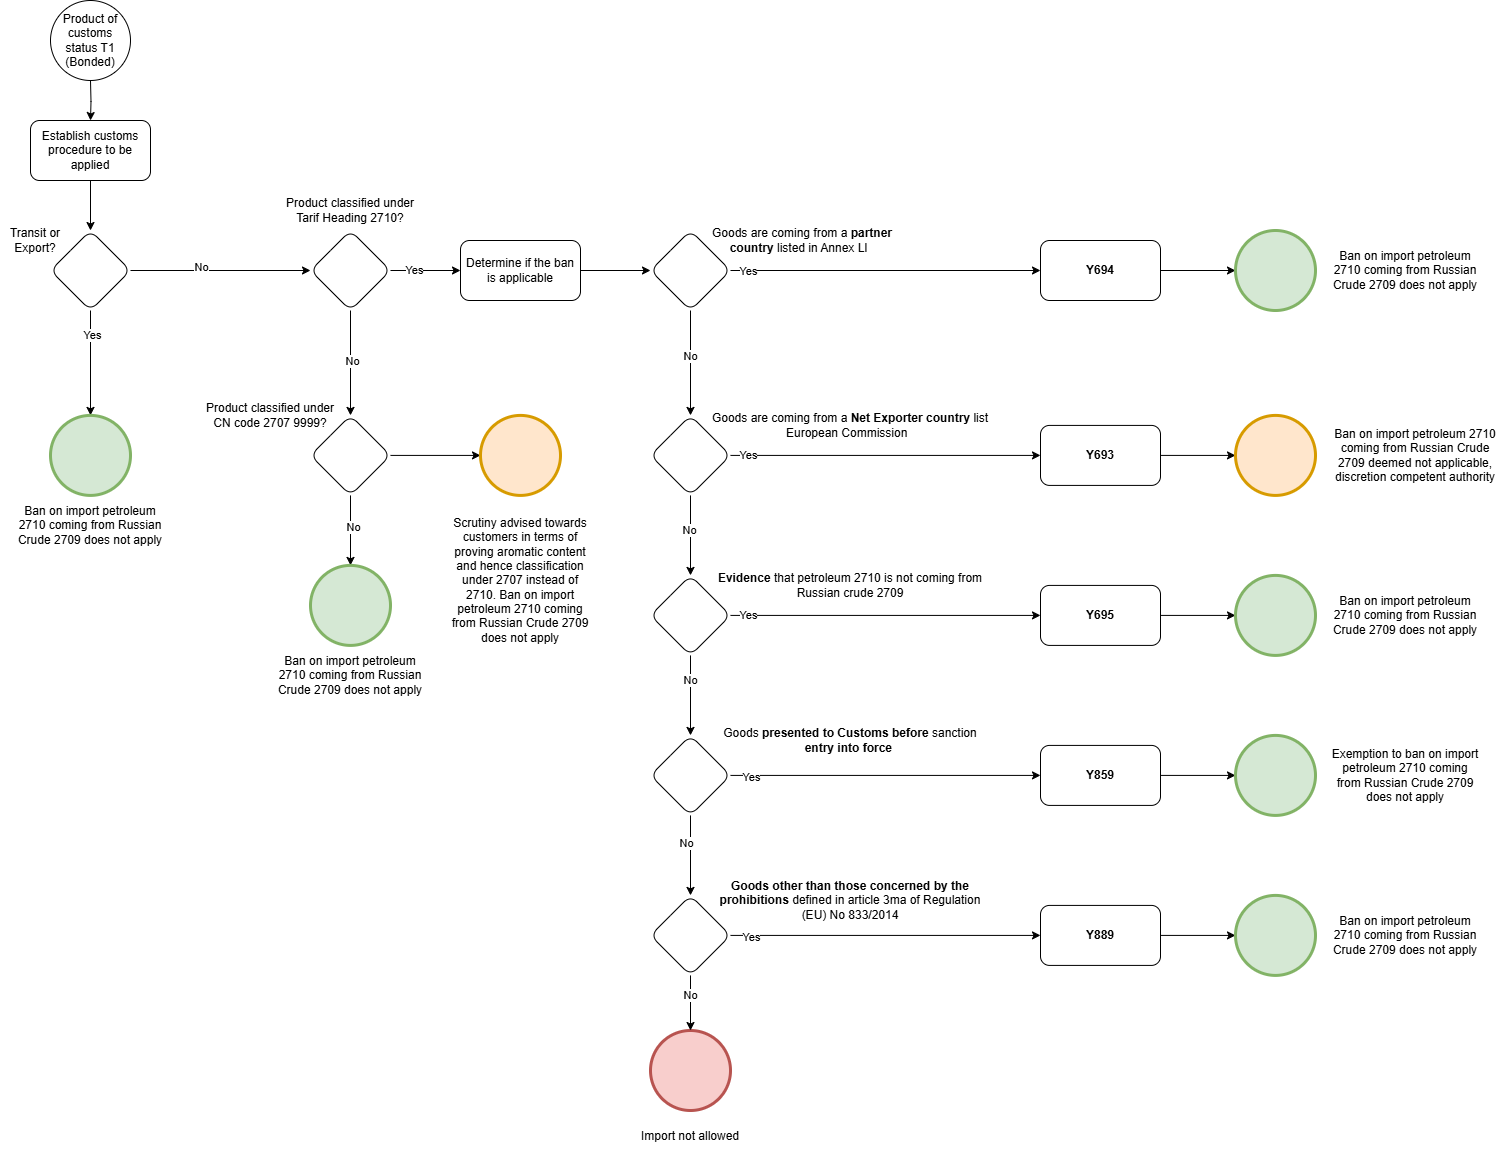
In the respective customs declarations for placing goods under the mentioned customs procedures in scope it should be stated on what grounds the ban does not apply. Below an overview of the respective codes.
Practical considerations. When the Measure apply a declaration will be rejected if no Y code is provided. In a real time declaration process this impacts operations directly, but at the same time offers a safeguard (i.e. on applying a Y code, not perse application of the correct code).
In declaration processes where a simplified manner applies, such as Entry Into the Declarants Record (EIDR) there is no real-time communication. In case of Customs warehousing also no supplementary declaration is required where a check is performed by the system of the customs authorities, unlike the supplementary declaration process for, for example, Inward Processing or the Release for Free Circulation.
This specific ban is limited to petroleum products falling under CN code 2710. Common in our industry is the handling of goods classified under CN code 2707 9999. This classification is primarily based on the aromatic content being > 50%. In most cases the aromatic content is the determining factor for classifying under Tariff Heading 2707 (i.e, > 50%) or Tariff Heading 2710 (i.e. ≤ 50%). Although the practical impact is unclear, two points of attention:
- There might be increased controls on customs declarations lodged for goods under CN code 2707 9999. This may cause operational interruptions. We understand that establishing the aromatic content is a relatively time-consuming process;
- Different methods lead to different results. In practice we have seen examples where different approved methods applied to determine the aromatic content lead to different outcomes and since this is the determining factor applied in the EU to determine the classification, there is an increased risk in non compliance.
Y693 - Net Exporter Countries of Crude Oil (2024)
Below is the official list of third‑country net exporter countries of crude oil (based on 2024 data) that benefit from the presumption that petroleum products (CN 2710) imported from them into the EU were obtained from domestic crude oil, not from Russian crude — unless competent authorities have reasonable grounds to suspect otherwise. This list is taken from the European Commission’s sanctions FAQ on the oil import ban (last update 29 October 2025).
(Imports from these countries are presumed not to be derived from Russian crude)
- Afghanistan*
- Albania
- Algeria
- Angola
- Antigua and Barbuda*
- Argentina
- Azerbaijan
- Bahamas*
- Barbados*
- Belize*
- Bhutan*
- Bolivarian Republic of Venezuela
- Brazil
- Burkina Faso*
- Burundi*
- Cabo Verde*
- Cambodia
- Cameroon
- Central African Republic*
- Chad*
- Colombia
- Comoros*
- Democratic Republic of the Congo
- Djibouti*
- Dominica*
- Ecuador
- Egypt
- Equatorial Guinea
- Fiji*
- Gabon
- Gambia*
- Ghana
- Grenada*
- Guatemala
- Guinea*
- Guinea‑Bissau*
- Guyana
- Iraq
- Islamic Republic of Iran
- Kazakhstan
- Kiribati*
- Kuwait
- Lesotho*
- Liberia*
- Libya
- Malawi*
- Maldives*
- Mali*
- Mauritania*
- Mexico
- Mongolia
- Mozambique
- Myanmar
- Nigeria
- Oman
- Palau*
- Papua New Guinea*
- Qatar
- Republic of Moldova
- Republic of the Congo
- Saint Kitts and Nevis*
- Saint Lucia*
- Saint Vincent and the Grenadines*
- Samoa*
- Sao Tome and Principe*
- Saudi Arabia
- Seychelles*
- Sierra Leone*
- Solomon Islands*
- Somalia*
- South Sudan
- Sudan
- Timor‑Leste*
- Tonga*
- Trinidad and Tobago
- Tunisia
- Turkmenistan
- United Arab Emirates
- Vanuatu*
* Countries for which only aggregated data across multiple countries is available; they are treated as net exporters for the purposes of the presumption.
How the Presumption Works
- Petroleum products imported from these net‑exporting countries are presumed to be produced from that country’s own crude, and therefore not derived from Russian crude oil.
- This presumption can be rebutted by customs authorities if there are reasonable grounds to believe the products were actually obtained from Russian crude (e.g., disproportionate imports or refined blends with Russian origin).
Notes
- This list is updated annually based on International Energy Agency net trade flow data.
- Even for net exporters, authorities may still ask for documentation if they suspect the presumption does not hold in specific cases.
Y694 - Partner Countries listed in Annex LI
Below the official list of partner countries in Annex LI of Council Regulation (EU) No 833/2014 — i.e., the countries whose petroleum product imports into the EU are exempt from the obligation to provide evidence of the origin of the crude oil used to produce the product (because those countries have equivalent restrictive measures in place):
As amended most recently (Annex LI to Regulation 833/2014):
- Canada
- Norway
- United Kingdom
- United States of America
- Switzerland
- Australia
- Japan
- New Zealand
This list defines the countries from which importers are not required to provide documentary evidence of crude oil origin for CN 2710 petroleum products imported into the EU under the sanctions import ban regime.
If petroleum products under CN 2710 are imported from one of these partner countries, the EU sanctions regime does not require submission of evidence about the crude oil used in refining (i.e., no affirmation that it is not derived from Russian crude).
Process flow - Import ban fuel 2710 coming from Russian Crude 2709
Example - Product CN 2710 petroleum product produced by a refinery in Bulgaria
Once refined in Bulgaria, the resulting CN 2710 product is an EU-produced product. The product is subsequently exported from the EU to Gibraltar against a customer order. Gibraltar is outside the EU.
If the product is not processed or substantially changed in Gibraltar and is subsequently returned to the EU, it is re-imported into the Netherlands using the re-import procedure (68 10), supported by an INF 3.
For sanctions purposes, the return from Gibraltar does not turn the product into a CN 2710 product obtained in a third country from Russian crude. The product was produced in Bulgaria, within the EU, before it was exported to Gibraltar. The fact that it temporarily leaves the EU and is subsequently returned from Gibraltar does not change its origin or the fact that no refining took place in Gibraltar.
The sanctions assessment therefore focuses on the crude/feedstock entering Bulgaria and the circumstances under which it was imported into the EU. Provided that the feedstock was lawfully imported and the applicable sanctions requirements were met, the subsequent export to Gibraltar and return to the EU under the re-import procedure do not, in themselves, create a new sanctions restriction under Article 3ma.
In this case, the use of Y889 in the re-import declaration relates to the applicable sanctions declaration for the returned goods, saying the Sanctions do not apply as per above explanation.
Background
Council Regulation (EU) 2025/1494 – EUR-Lex
Y889 itself is not contained in Regulation 2025/1494. Y889 is a TARIC/customs declaration code created to operationalise Article 3ma in customs declarations. The TARIC measure identifies its legal basis as Regulation 833/2014, with the measure becoming applicable on 21 January 2026. Current TARIC data describes Y889 as:
“Goods other than those concerned by the prohibitions defined in article 3ma of Regulation (EU) No 833/2014.”
So the chain is:
Regulation 2025/1494 → Article 3ma introduced → TARIC import measure created → Y693/Y694/Y695/Y859/Y889 document codes established.
The rationale for Y889 is particularly relevant to your Bulgarian case.
Article 3ma does not prohibit all CN 2710 products coming from third countries. It prohibits:
“petroleum products falling under CN code 2710 obtained in a third country from crude oil falling under CN code 2709 00 originating in Russia.”
Consequently, there are two fundamentally different situations:
The product is within the scope of Article 3ma, but the prohibition does not apply because one of the mechanisms in Article 3ma applies. For example:
Y694 — imported from an Annex LI partner country;
Y695 — evidence of the crude oil origin;
Y693 — presumption for petroleum products from a third country that was a net exporter of crude oil.
The product is not concerned by Article 3ma at all.
That is what Y889 addresses.
This distinction is important. Y889 is not really an “exemption” from Article 3ma. It is a declaration that the goods fall outside the substantive prohibition.
This is also confirmed by customs guidance. Swedish Customs, for example, specifically states that where a petroleum product does not contain crude oil, the importer should enter Y889 and be able to substantiate what the product actually contains. (Tullverket)
If you are importing a CN 2710 product from Gibraltar, you cannot simply use Y889 because the product is ultimately associated with a Bulgarian refinery. You have to ask whether, at the moment of the import into the EU, the goods are “petroleum products … obtained in a third country from crude oil … originating in Russia.”
If the product was refined in Bulgaria, then the refining took place inside the EU. Article 3ma is specifically directed at 2710 products obtained in a third country from Russian 2709 crude. Bulgaria is not a third country.
If the same product subsequently goes to Gibraltar and returns to the EU without further refining, the Gibraltar leg does not turn it into a product “obtained in a third country from Russian crude.”
Hence, in principle, no sanctions restriction under Article 3ma applies to the re-importation of the product, as the CN 2710 product was obtained in Bulgaria, an EU Member State, and not in a third country. The subsequent export to Gibraltar and return to the EU does not change this.
For the customs declaration, it is assumed that the TARIC/customs declaration system requires a Y-code where the Article 3ma measure is triggered. In that practical situation, Y889 is considered the most suitable code, as it confirms that the goods are not concerned by the substantive prohibition of Article 3ma.
If the TARIC Article 3ma measure is triggered by the declaration, Y889 can be used to state that the goods are outside the substantive scope of Article 3ma.
If the measure is not triggered because the goods have EU origin, there is no reason to insert Y889 merely because the goods physically arrive from Gibraltar. The Customs declaration system should not apply the related Measure based on the Commodity code plus the origin being EU. This shows in the Tariff information website of, among others, Dutch Customs. So although including a Y code should not be needed in such a case, if in practice the Customs declaration system blocks because it does require a Y code, then Y889 is the correct option. Theory and practice are not always aligned.
Y889 was introduced as the generic negative declaration required to make the Article 3ma TARIC measure workable for goods that meet CN 2710 but are outside the substantive scope of Article 3ma. It was not introduced by the Regulation as a new substantive exemption.